Underwriting by LDP, ProFun, Savills, IHG, Dar Al Qias and ZFP
Each brief states what the study provides and how the financing model uses it; where a study's own figures have been superseded, the brief says so.
 LDP · Leisure Development Partners
Experience Centre market, benchmark & attendance study — Report 6.0
Madinah and religious-tourism demand, international benchmarks of immersive attractions, entertainment-value pricing (SAR 78 per visit) and attendance of 1.19M visitors by 2031 — the attendance basis ProFun adopted. LDP's more conservative 31%-margin revenue case is carried in the model as the Centre downside sensitivity.
Opens in a new tab · PDF
 Savills
Retail tenant mix, rents and pro-forma — 24 July 2024
Positioning of the boulevard, unit-by-unit tenant mix, indicative rents by category (SAR 500–1,900/sqm), occupancy ramp 50/70/92%, service-charge, specialty-leasing and sponsorship income, and SAR 39.7M of landlord fit-out contributions. Savills priced 53,987 sqm (48,467 + optional mezzanine) at SAR 52 / 67 / 82M in years 1–3. The model keeps Savills' mix and scales every income line to the 38,597 sqm Phase 1 GLA (× 0.715); expansion to Savills' recommended area is a later retail phase.
Opens in a new tab · PDF
 IHG Hotels & Resorts
Staybridge Suites feasibility (FAP) and financial projections — 2025
Brand feasibility for a 300-key Staybridge Suites and the per-key economics used to underwrite the 600-key scheme: occupancy 57→63%, ADR SAR 590→660, RevPAR SAR 336→398, GOP 44→47%, fee structure and FF&E reserve. IHG has since withdrawn; the projections remain the underwriting benchmark and the 300-key case is a sensitivity.
Opens in a new tab · PDF
IHG Hotels & ResortsHotel financial projections (Excel) — August 2025
Ten-year P&L for a 300-key Staybridge Suites: occupancy, ADR, departmental and undistributed costs, management fees and NOI (38–39%). The model's hotel ramp (90.5% / 95.2%), rooms share (83.4%), ADR growth (2.2%) and GOP margins (44.2 / 46.1 / 47.4%) are taken from this file and applied per key to 600 keys.
Opens in a new tab · XLSX
 ProFun Management Group
Experience Centre business plan for Midwam — Rev. 1, January 2025
Operator's pro-forma business plan and the Centre's base case: attendance of 1.14M visitors in 2028 rising to 1.55M by 2040 (LDP's forecast), revenue per visitor SAR 92→121, a 13-year consolidated P&L (p.59) with EBITDA after management fees of 35.5%→43.2%, staffing, marketing and a SAR 36.4M pre-opening budget. The model uses this pro-forma line by line.
Opens in a new tab · PDF
 Dar Al Qias
Land valuation analysis — final report, 21 March 2024
Market rental value of the Al-Maqr leasehold — SAR 16.5M/yr on 205,365 sqm against the SAR 2.39M contract rent — and the NPV of the rent saving (SAR 71.2M). The site has since grown to 245,337 sqm; the model pro-rates the saving to ≈ SAR 85M as the interim value of Koushan's in-kind contribution pending a certified valuation. The report's own development appraisal predates the current programme and is not used.
Opens in a new tab · PDF
 Zuhair Fayez Partnership
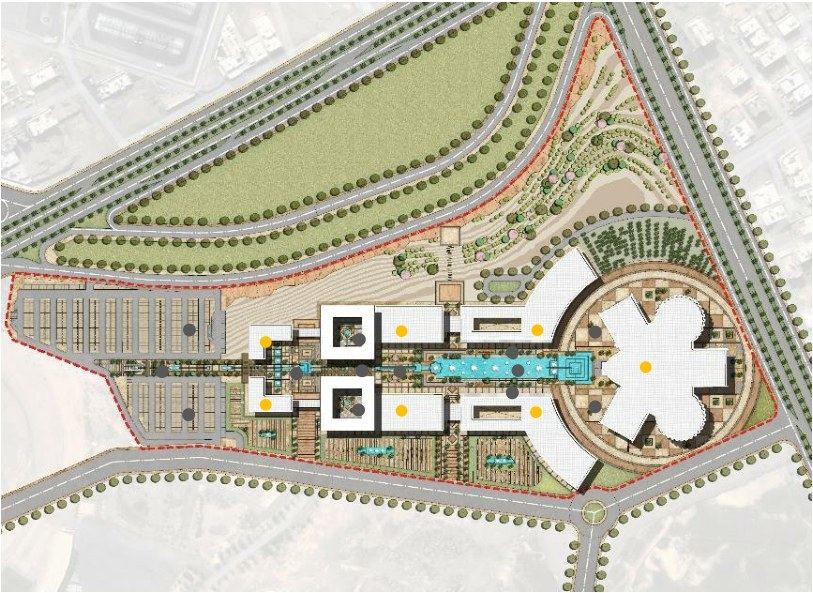
Masterplan concept design — February 2025
Masterplan, architectural concept, water axis, facades and the February 2025 hard-cost estimate for the boulevard and Experience Centre that Watanco's SAR 550M guaranteed maximum price superseded.
Opens in a new tab · PDF
 Watanco & ZFP
Hotel concept design — December 2025
Pre-concept design for the 600-key hotel (300 hotel keys + 300 serviced apartments): site analysis, massing inspired by Ayer Mountain, 29,152 sqm BUA, room matrix, floor plans and perspectives. Hotel FF&E of SAR 50M and pre-opening of SAR 15M are carried in the model.
Opens in a new tab · PDF