Business case & financing proposal · prepared by Koushan for Watanco Contracting Co. and its financing banks · October 2026

MAYADEEN PARK

Al-Madinah Al-Munawwarah · King Fahd Park. A SAR 550 million Seerah-themed destination — Experience Centre and F&B boulevard, with a 600-key hotel as Phase 2 — fifteen minutes from the Prophet's Mosque.

SAR 550MTotal investment, capped
19.7%Yield on cost, 2032
19.3%Project IRR, unlevered
2034Loan repaid from cash flow
Watanco64% · Funding partner & EPCF contractor
Koushan36% · Developer & asset manager

Studies & documents   SPV financials   Download the deck (PDF)

Transaction summary

Watanco funds the SPV through an interest-free shareholder loan and seeks a term facility of up to SAR 568 million

Watanco Contracting Co. (64%) provides the Mayadeen Park SPV with an interest-free shareholder loan that funds 100% of the SAR 550M development cost, pre-opening included, and raises its own financing against it. Every riyal of SPV cash repays that loan before any dividend is paid, and the whole project is available as collateral to Watanco's financing banks.

  • Fixed-price delivery: SAR 550M guaranteed maximum price under the Master EPCF Agreement (13 July 2026), now absorbing all pre-opening; Watanco is both funder and contractor, so overruns stay with the same party
  • Land secured: 245,337 sqm Al-Maqr leasehold to 2074 at SAR 2.39M fixed rent + 2% of revenue; development and hotel permits in place
  • Phase 1 (retail + Experience Centre) opens Q4 2028; the 600-key hotel follows as Phase 2 from 2027 once the construction permit and Al-Maqr approval are in hand, opening mid-2029
  • Watanco receives SAR 102–110M a year in 2031–34 under a 100% cash sweep
SAR 499MPeak funding need, 2029
SAR 109MSPV NOI 2032, after operator fees, SPV overheads and land rent
21.2%Project IRR with a 2040 exit at 10% cap
2.1xCompletion value ÷ cost on a conservative 10% cap
The destination

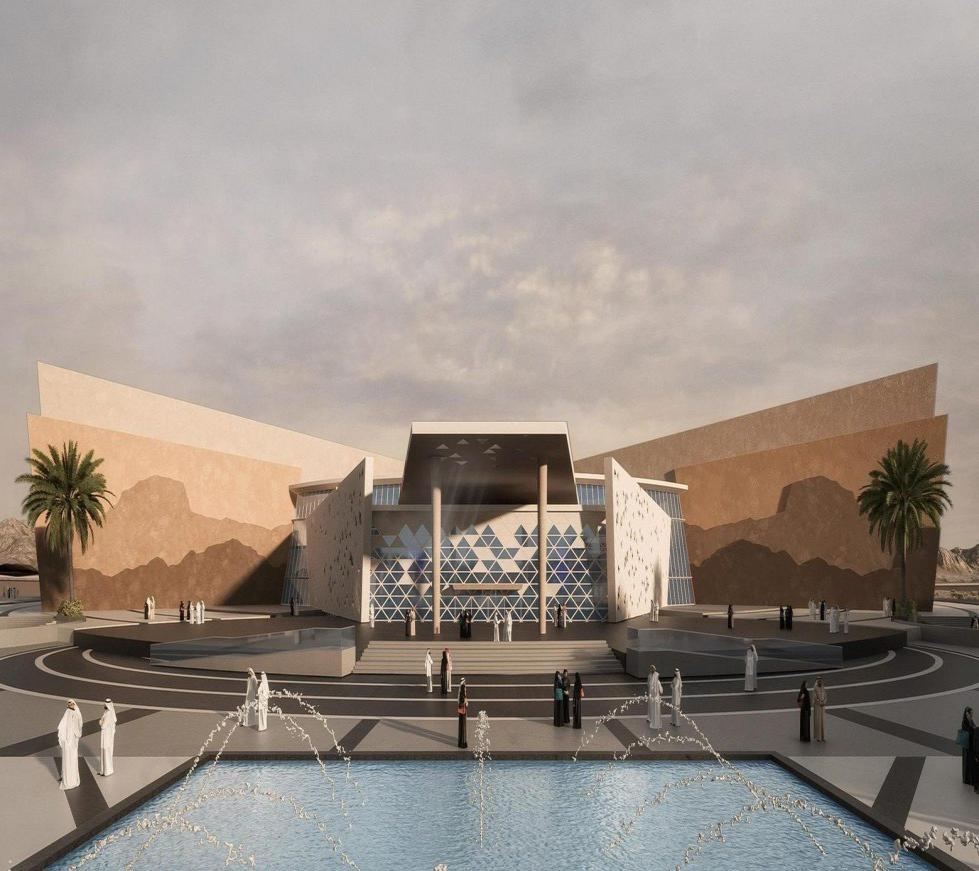
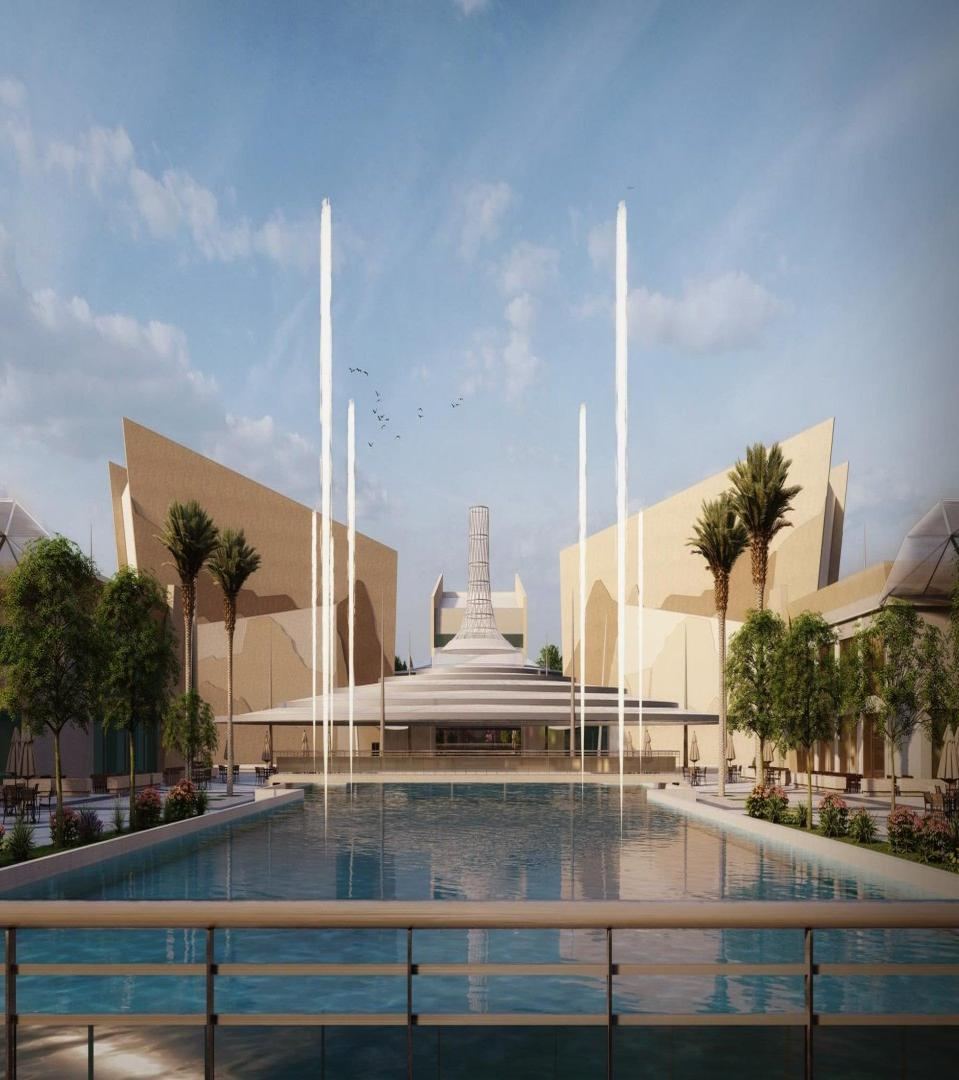
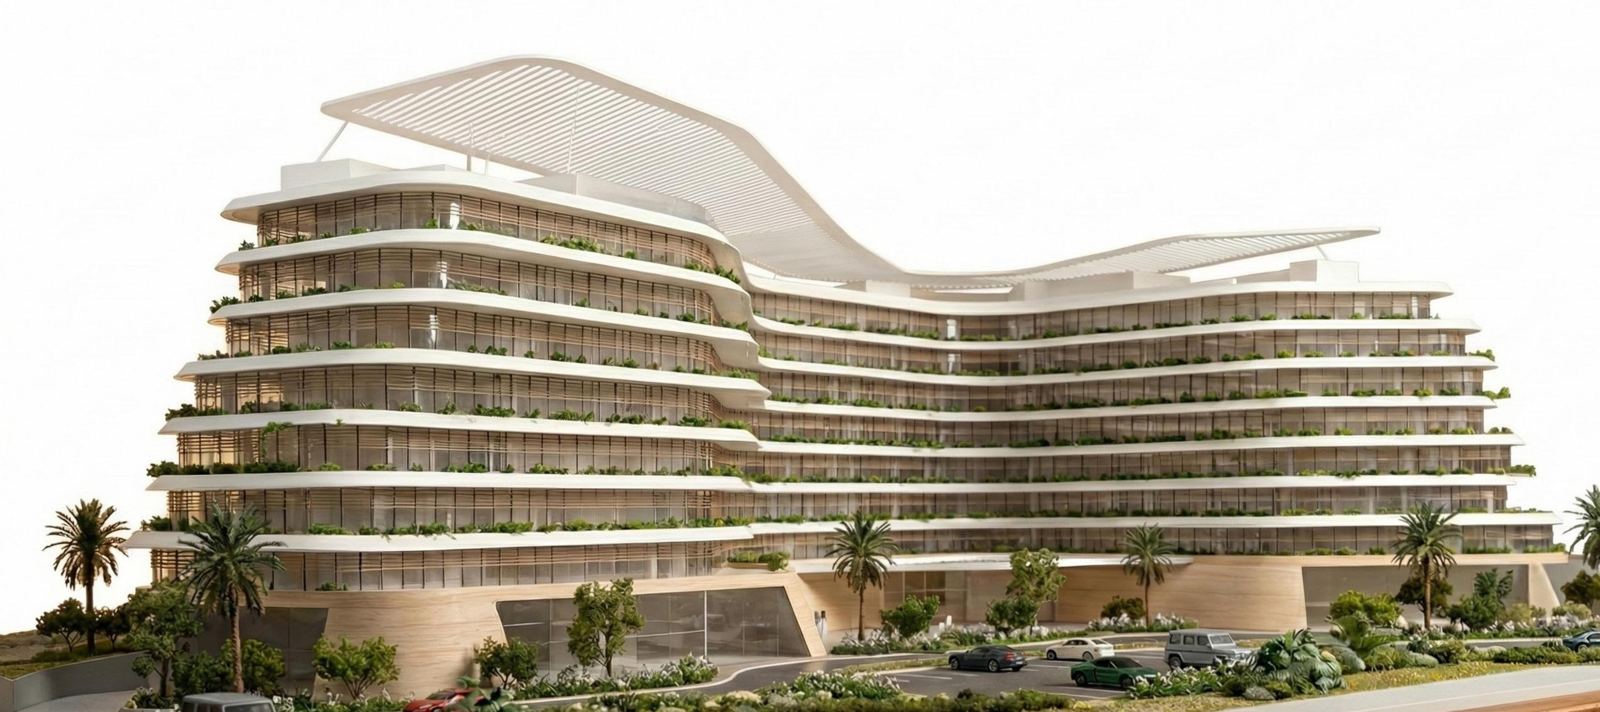
Where the Seerah comes to life — three engines, one destination

The market

Madinah: deep, growing, under-served

Visitors stay several nights in Madinah, yet modern cultural and family experiences are scarce. The Guests of Allah programme is building structured itineraries — Mayadeen is designed as a stop on them, with shuttle links to the Prophet's Mosque.

75%Madinah hotel occupancy in 2025, a three-year high
6.45MReligious visitors in Q1 2025, +10.7% y/y
13 → 25MAnnual visitors 2023 → 2030 target
SAR 17KAverage spend per pilgrim

Sources: Al-Maqr hospitality report via TradeArabia (2025); Ministry of Tourism; GASTAT; Global Muslim Travel Index; LDP Report 6.0.

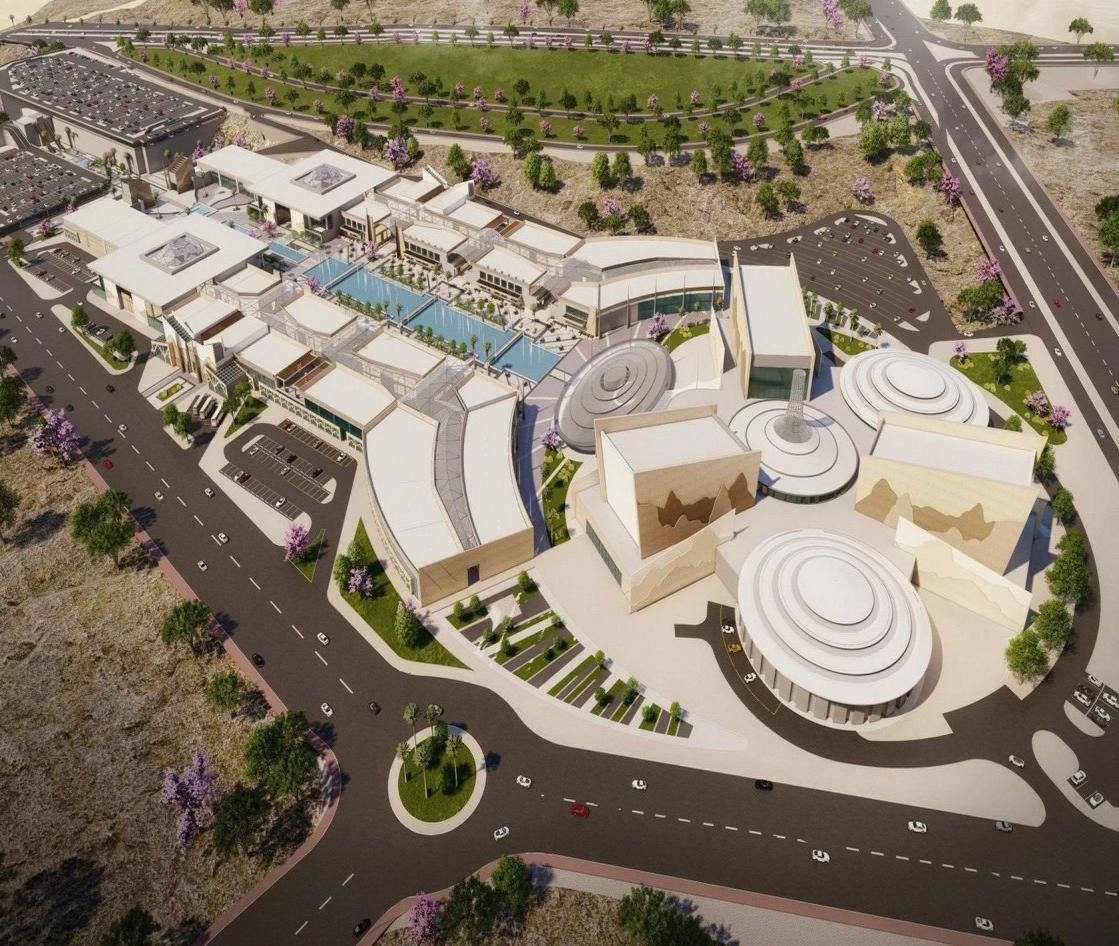
Aerial masterplan
The site

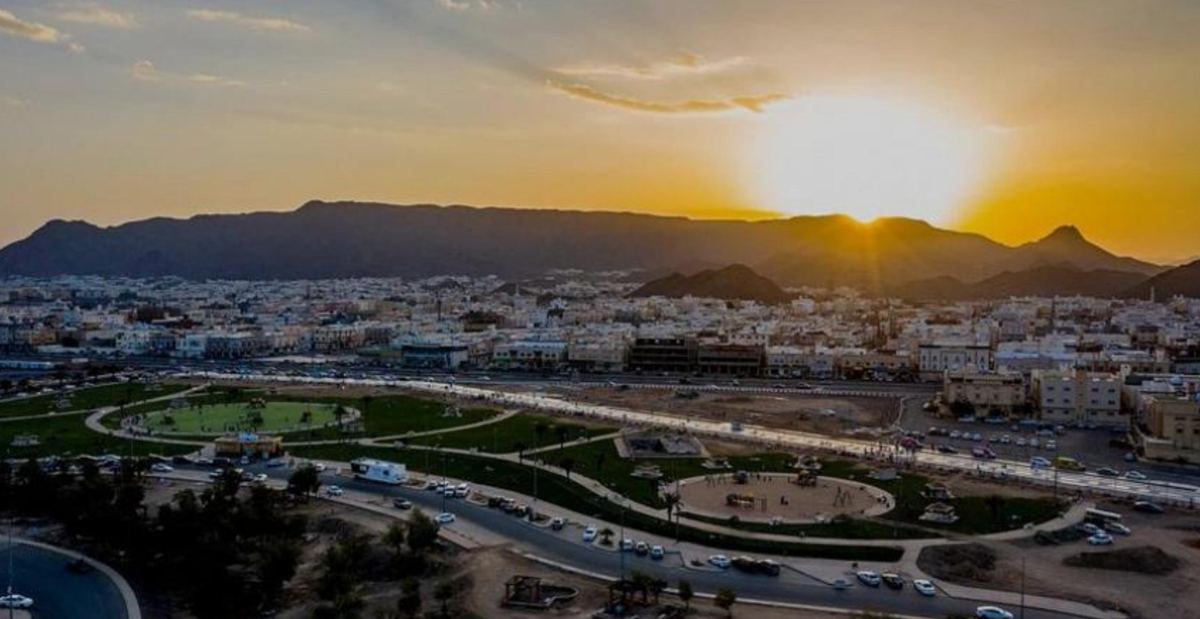
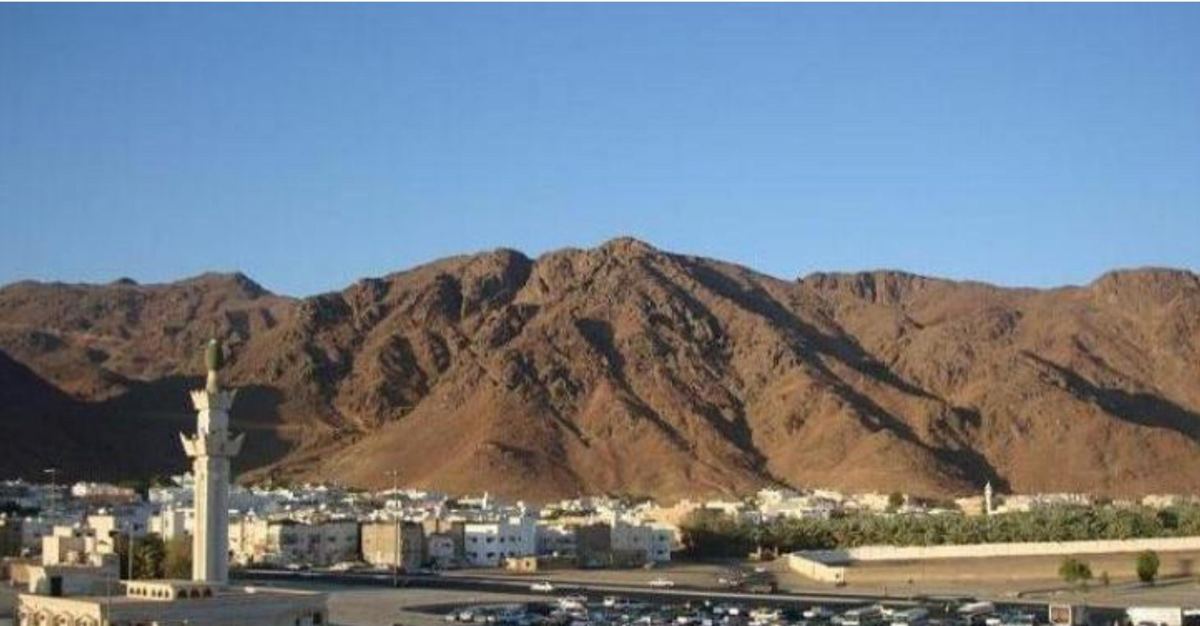
245,337 sqm at King Fahd Park, 15 minutes from the Haram

TenureAl-Maqr (investment arm of Madinah Amanah) contract 23/007, Aug 2023; 50-year usufruct to April 2074
RentSAR 2.39M fixed per year + 2% of SPV revenue — under 3% of revenue; rent-free to 15 April 2028
ValuationDar Al Qias (Mar 2024): market rent SAR 16.5M/yr — the contract rent is ~85% below market; pro-rated to the full site the saving is worth ≈ SAR 85M (NPV)
PermitsDevelopment permits in place; hotel permit issued with site-wide commencement under the lease

Site location & documents

Delivery & partners

De-risked: the groundwork is done

Investment agreement

Contract 23/007 with Al-Maqr (Aug 2023); 50-year usufruct over 245,337 sqm, handed over April 2024. Phase 2 (hotel) proceeds once the construction permit and Al-Maqr's approval are obtained.

Design & studies

Masterplan and detailed design by Zuhair Fayez Partnership; hotel concept by Watanco & ZFP; feasibility by KPMG, LDP and Savills; ProFun operator plan; IHG projections.

Partnership & GMP

Master EPCF Agreement signed 13 July 2026: SAR 550M guaranteed maximum price, 24-month programme; enabling works under way since Aug 2025.

Two aligned partners, each paid from the project's success

Watanco

Watanco Contracting Co.

64% · Funding partner, EPCF contractor & construction manager

Provides an interest-free shareholder loan for the full funding need, repaid from 100% of SPV cash before any dividend, and raises its financing with the project as collateral. Madinah-based general contractor (est. 1435H) delivering design completion, procurement and construction under a SAR 550M guaranteed maximum price; funds any overrun. Track record includes Al Seeh Plaza Hotel and municipal works in Madinah.

Koushan

Koushan Real Estate Development

36% · Developer & asset manager
Originated the project and holds the land rights, masterplan, designs and permits; established the SPV and holds reserved matters. The asset-management role is covered within the SPV's AM & G&A overhead — no separate fee.

Structure

Ownership and funding structure

Watanco's financing banks
Term facility · security over the project
→
Watanco Contracting Co.
Borrower · 64% shareholder · EPCF contractor at SAR 550M GMP
→
Mayadeen Park SPV
Interest-free shareholder loan · 100% cash sweep until repaid

Shareholders

64%Watanco — shareholder loan for the full funding need; EPCF at SAR 550M GMP
36%Koushan — land rights, design, permits; asset manager (no separate fee)

Cash waterfall

  1. Operating costs, land rent, SPV overheads, zakat
  2. Minimum cash SAR 10M
  3. Shareholder loan repaid in full — interest-free, senior to all equity
  4. Distributions 64 / 36

The 64/36 shareholding and shareholder-loan treatment are agreed; the amendment to the Master EPCF Agreement and the shareholders' agreement are being documented.

See the SPV financials, exhibit and sensitivities →

Financial highlights

Revenue builds to SAR 285M by 2031; the loan repays itself by 2034

SAR 285MRevenue 2031 — hotel 38%, Centre 42%, retail 21%
SAR 109MSPV NOI 2032
SAR 499M → 2034Shareholder loan peak → fully repaid
17.3%Watanco IRR with a 2036 exit · 4.2x
Debt capacity

Illustrative facility: the project carries the debt

SAR 568MPeak facility incl. SAR 69M capitalised profit
2037Facility repaid under 100% cash sweep
2.38xMinimum interest cover (2030)
53%Peak loan-to-value on lender's completion value

Placeholder terms (6.5%, 4-year grace with capitalised profit, 100% cash sweep) for sizing only; tenor, pricing, grace, currency and security to be agreed. Every sensitivity tested — including a hotel at IHG's 300-key level, the Centre at LDP's lower case and Phase 1 on its own — repays the shareholder loan. Full sensitivities →

Protections

Why the facility is well protected

Fixed-price delivery

SAR 550M guaranteed maximum price from Watanco, itself the 64% shareholder and funder; any overrun is funded by Watanco.

Senior to all equity

The shareholder loan is repaid from 100% of SPV cash before any dividend — no lender and no distribution ahead of it.

Whole project as collateral

Pledge over SPV shares, assignment of the shareholder loan and project cash flows, and security over the Al-Maqr usufruct (subject to lessor consent).

Low-cost government land

SAR 2.39M fixed rent plus 2% of revenue — under 3% of revenue, ~85% below the Dar Al Qias market rent.

Three uncorrelated engines

Hotel 38%, centre 42%, retail 21% of revenue; the loan is repaid even with all revenue 20% below plan or the Centre at LDP's lower case.

Aligned partners

Developer and contractor are paid through the same waterfall; Koushan's 5% fee is on retail revenue only and distributions follow repayment.

Next steps

Proposed path to financial close

1

Indicative terms

Nov 2026

Term sheets from Watanco's financing banks: amount, tenor, pricing, grace, currency, security and covenants.

2

Due diligence

Nov–Dec 2026

Audited financials of Watanco and Watanco; independent technical adviser on GMP and programme; legal opinion on Saudi security and the Al-Maqr usufruct.

3

Conditions precedent

Dec 2026

Amendment / SHA for 64/36; certified in-kind valuation; written Al-Maqr confirmation of the rent-free period; hotel construction permit and Al-Maqr approval (Phase 2); operator shortlist.

4

Financial close

Q1 2027

Facility agreement; first drawdown against Watanco's approved cash-flow forecast.

Everything behind this page is one click away: the deck, the financing model and component models, the Master EPCF Agreement, the Dar Al Qias valuation and the LDP, Savills, IHG, ProFun and KPMG studies.
Open the studies & documents page